
If you're a top-down macro trader/investor like I am, you know there are good times to invest in a certain sector and bad times to do so. That's why we go "top-down" from the macro to the sectors, rather than "bottom-up" buying of favored stocks/sectors and hoping the macro will be permissive. Often, it will not be.
As we have been noting for a long time now, the 2026 macro has not been conducive to sustained successful investing in the precious metals sector. The sector got way overdone in Q1, and the correction drags on into its final stages.
In a previous article, Gold Stock Correction Dynamics under the sub-heading The Miners Leverage The Metal, we noted:
That is the most important point about gold miners that many people get wrong or only half right. For many years, there was constant complaining in the gold "community" about how the miners had lost their vaunted leverage to the price of gold. Well, that is not at all the case. Of course, the miners leveraged gold to the downside! Bloated of their own premium valuations and increasingly shoddy operating practices during the 2003-2007 bull market phase, they leveraged gold's under-performance vs. mining cost inputs (notably crude oil) into the crash of 2008 and then a long bear market into 2016. It was logical leverage, and it was rightly negative.
With the 2026 correction now taking a perhaps final decline during its ending stages, it is time to consider buying opportunities ahead (with "a boatload of patience" per the linked article).
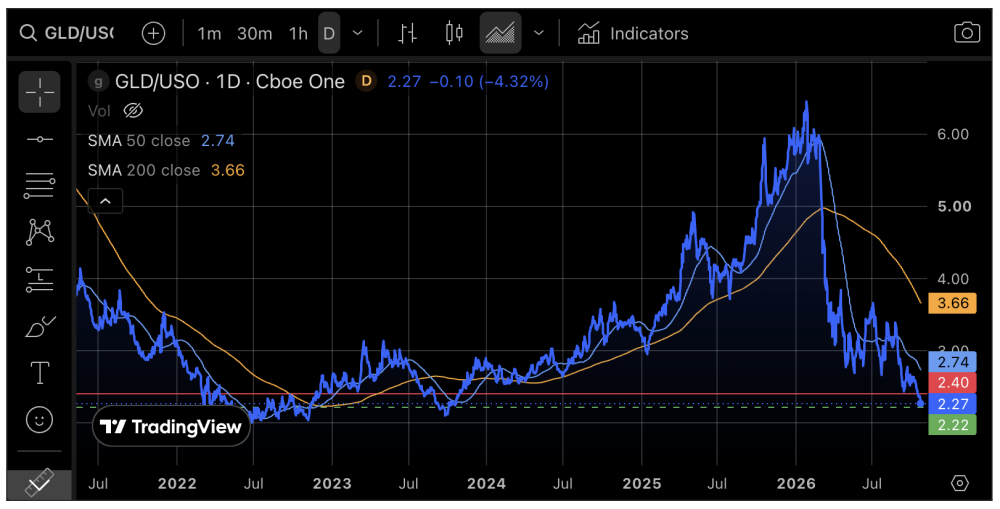
However, as things stand currently, gold (miners' product) is still getting drubbed in relation to a primary cost input (crude oil). That situation is expected to change, but as you can see, Gold/Oil (GLD/USO) is in the dumps and showing no sign of a bottom yet.
Royalty Vs. Mining
First, a disclaimer. I own precious metals royalty/streamers Royal Gold Inc. (RGLD:NASDAQ), Wheaton Precious Metals Corp. (WPM:TSX; WPM:NYSE), and the smaller, younger Orogen Royalties Inc. (OGN:TSXV; OGNNF:OTCQX). No actual miners are held currently. I decided to hold these two, along with a few stocks in sectors that are being rotated in rather than out, because cash is very high and risk is well-managed. Aside from a couple of exploration specs, that is all I hold (along with a boatload of cash and equivalents paying income) in the precious metals sector.
Again, the time is coming to flip bullish, but short of the proper macro-fundamental backdrop engaging (while beyond the scope of this article, we note that a few signs are already in play), that time is not yet. Hence, there are reasons I hold two royalties and no actual miners. The chart above and the upcoming earnings season are the main reasons.
While the royalty stocks will likely be weak if the sector is weak, they would primarily be impaired by the nominal weakness in the metals only. Whereas gold and silver mining stocks would be impaired by both nominal metals prices AND the negative leverage they currently get from gold's horrible standing in relation to mining cost input, oil.
As gold resumes its dive in oil terms, notice what the ratio of Royal Gold to the broad sector (GDX) is doing. Notice also how during 2025, a macro phase when gold mining leverage to gold was positive (with the Gold/Oil ratio above rising), RGLD greatly under-performed. Not rocket science, folks. That was leverage working positively.
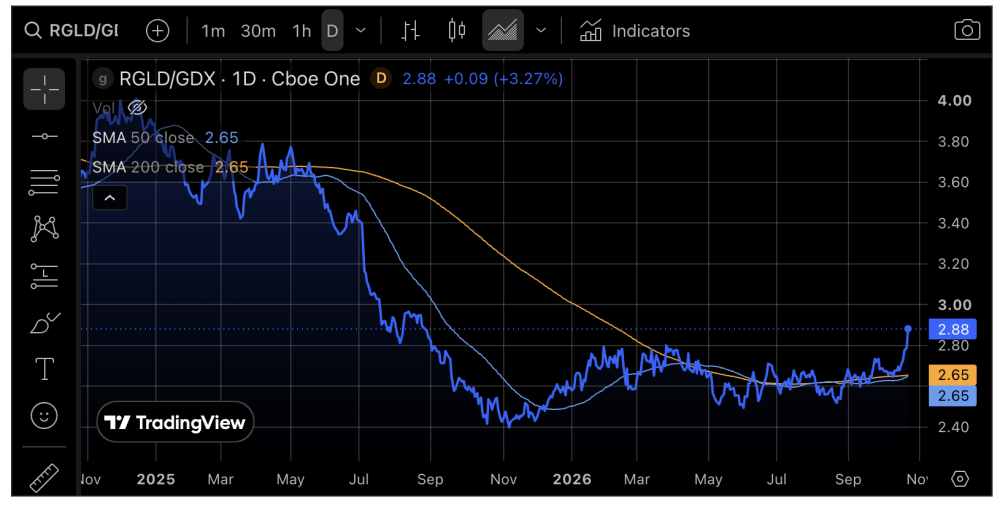
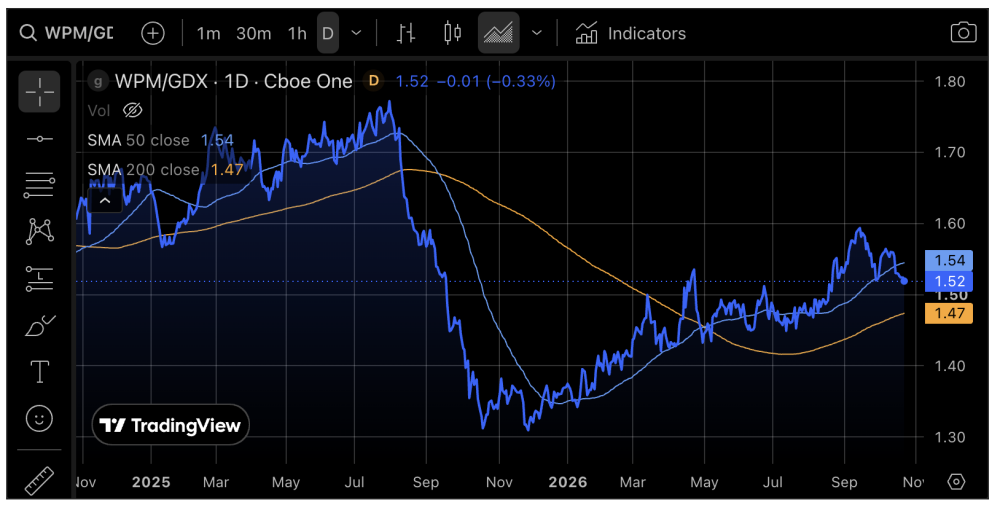
Interestingly, WPM/GDX is down of late, but it has maintained an uptrend all through a bearish 2026.
Indeed, while RGLD/GDX is trying to establish a bottom/base breakout and upturn, WPM/GDX has already turned its moving average trends up.
Bottom Line
Earnings season is upon us, and the Gold/Oil ratio indicates cost-related pressure on mining operations. Have the miners fully discounted that? We'll find out shortly. However, with the sector's technicals breaking down into what could be a classic buying opportunity, patience is the way to go.
Also, when first stepping back in, the implied safer bet would be to add quality royalty stocks before miners until we find a clear technical bottom in the sector and fundamentals like Gold/Oil turn up. These things could happen in a flash (crash and reversal) or over an extended grind. We'll have to evaluate as info becomes available.
In addition to RGLD, WPM, and OGN.V/OGNNF, my favored precious metals royalty watch list items for future buying are Franco-Nevada Corp. (FNV:TSX; FNV:NYSE), Triple Flag Precious Metals Corp. (TFPM:TSX; TFPM:NYSE), and Vox Royalty Corp. (VOXR:TSX; VOXR:NASDAQ). There are others that will populate the list as well.
NFTRH was bullish in 2025, guarded, bearish, and now opportunistic in 2026, and the upcoming months should be rewarding. There is nothing like being prepared when this volatile sector takes a real nose dive, and the fundamentals flip positive.
We are not there quite yet, and the royalties are leading, as they logically should be. One day, when the sector's fundamental backdrop has fully turned, we'll look for the opposite, with quality miners aplenty tanking currently in service to future opportunity as positive leverage returns.
Just a few I have on watch are Equinox Gold Corp. (EQX:TSX; EQX:NYSEAMERICAN), Coeur Mining Inc. (CDE:TSX; CDE:NYSE), Alamos Gold Inc. (AGI:TSX; AGI:NYSE), and Agnico Eagle Mines Ltd. (AEM:TSX; AEM:NYSE). There are many more. If all goes well, they can be bought while the herd pukes them even as the fundamentals turn.
You can view more from Gary here.
| Want to be the first to know about interesting Silver and Gold investment ideas? Sign up to receive the FREE Streetwise Reports' newsletter. | Subscribe |
Important Disclosures:
- As of the date of this article, officers, contractors, shareholders, and/or employees of Streetwise Reports LLC (including members of their household) own securities of Royal Gold Inc., Orogen Royalties Inc., Franco-Nevada Corp., Triple Flag Precious Metals, and Agnico Eagle Mines Ltd.
- Gary Tanashian: I, or members of my immediate household or family, own securities of: Royal Gold Inc., Wheaton Precious Metals Corp., and Orogen Royalties Inc. My company has a financial relationship with: None. My company has purchased stocks mentioned in this article for my management clients: None. I determined which companies would be included in this article based on my research and understanding of the sector.
- Statements and opinions expressed are the opinions of the author and not of Streetwise Reports, Street Smart, or their officers. The author is wholly responsible for the accuracy of the statements. Streetwise Reports was not paid by the author to publish or syndicate this article. Streetwise Reports requires contributing authors to disclose any shareholdings in, or economic relationships with, companies that they write about. Any disclosures from the author can be found below. Streetwise Reports relies upon the authors to accurately provide this information and Streetwise Reports has no means of verifying its accuracy.
- This article does not constitute investment advice and is not a solicitation for any investment. Streetwise Reports does not render general or specific investment advice and the information on Streetwise Reports should not be considered a recommendation to buy or sell any security. Each reader is encouraged to consult with his or her personal financial adviser and perform their own comprehensive investment research. By opening this page, each reader accepts and agrees to Streetwise Reports' terms of use and full legal disclaimer. Streetwise Reports does not endorse or recommend the business, products, services or securities of any company.
For additional disclosures, please click here.